In April of this year, national market research marked a milestone that we’ve been waiting on since Covid market dynamics ravaged the office and industrial sectors. Vacancy rates for office and industrial properties declined at the same time for the first time in six years.¹ By the end of the second quarter, the recovery had firmed up further. National office vacancy fell to 13.4%—its fourth consecutive quarterly decline—while industrial vacancy tightened to 3.3%, and Canadian businesses took up more than 7.1 million square feet of additional industrial space in the quarter.² After six years of pandemic disruption, the fastest rate-hiking cycle in a generation, and a tariff dispute with our largest trading partner, the national market finally appears to be finding its footing. So what does a national turning point mean for the Okanagan, a market that never really participated in the turmoil to begin with?
I would argue it means quite a lot, just not in the way the headlines suggest. The Okanagan’s story this cycle has been one of quiet consistency—and consistency is starting to look like a competitive advantage. Greater Kelowna’s office market ended 2025 with vacancy at 8.6% after 38,000 square feet of positive absorption, led by Class A space. Compare that to the national office vacancy rate of 13.4% and the gap is striking: roughly five percentage points in a market segment that was widely written off only a few years ago. Kelowna’s office market never suffered the hollowing out that hit the major downtowns, which means it enters this recovery with far less ground to make up.
In Kelowna, we saw that stability show up in real transactions this quarter. In April, a 7,930 square foot, Class A strata office property in the Airport Business Park sold for more than $4 million, a strong result for a non-standard office product at a time when lenders across the country remain cautious on the asset class. In July, the Stober Group, behind the region’s flagship office district, the Landmark District, announced a four-storey, roughly 50,000 square foot healthcare hub for central Kelowna. I read that announcement in two ways—first, it is a clear vote of confidence in this region’s growth; second, it is also a reminder that even our most established local developers are diversifying beyond traditional office, and that the recovery in this asset class will be selective rather than universal.
The industrial market deserves a more careful telling, because the local data does not yet match the national mood, and I would rather be honest about that than write the story people expect. Nationally, industrial conditions have tightened decisively, with vacancy in most major markets now sitting between 2% and 3% and asking rents beginning to stabilize after several quarters of decline. Locally, the most recent published research describes a steadier picture. Kelowna’s industrial vacancy held roughly flat through 2025 with modest negative absorption balanced by consistent leasing, while West Kelowna’s vacancy rose as several larger projects reached completion, and sale prices and land values continued to drift lower. Smaller markets tend to follow the major centres with a lag of a few quarters, and with new industrial construction in the Central Okanagan slowing considerably, the space delivered in West Kelowna should be worked through rather than compounded. For now, the fair description of Okanagan industrial is resilient, not resurgent.
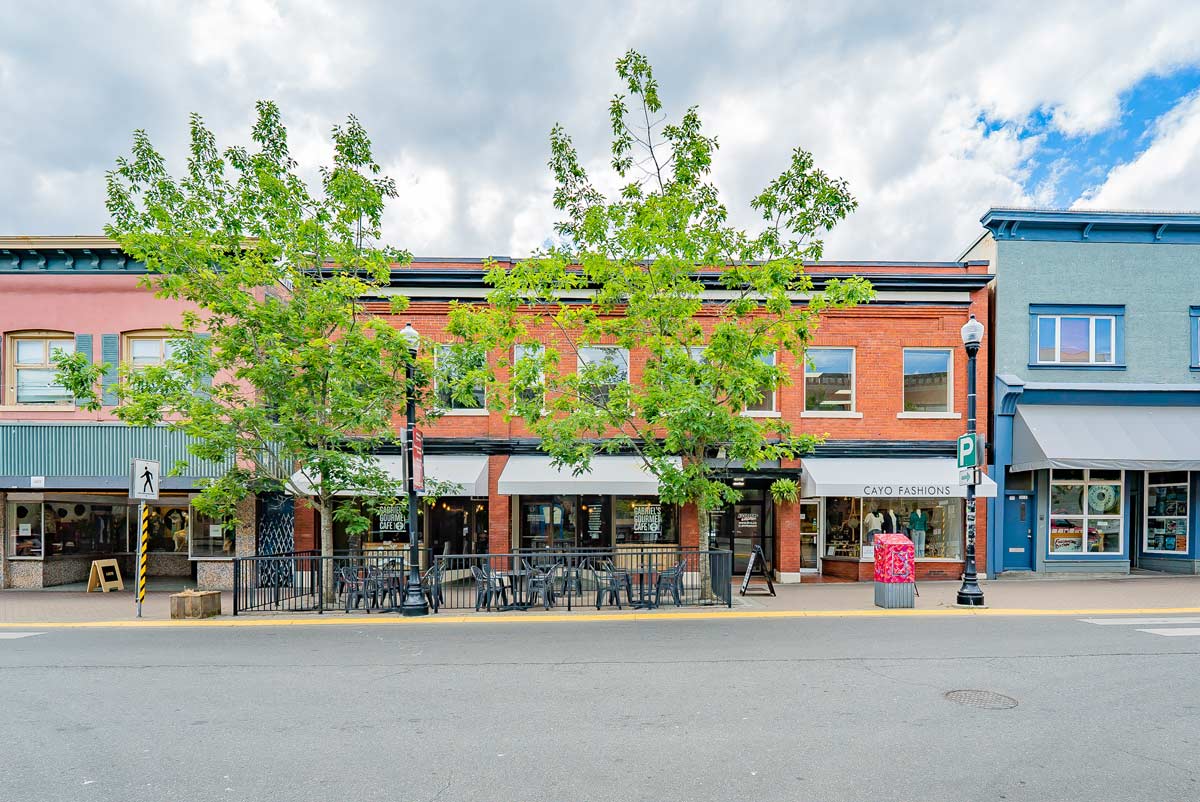
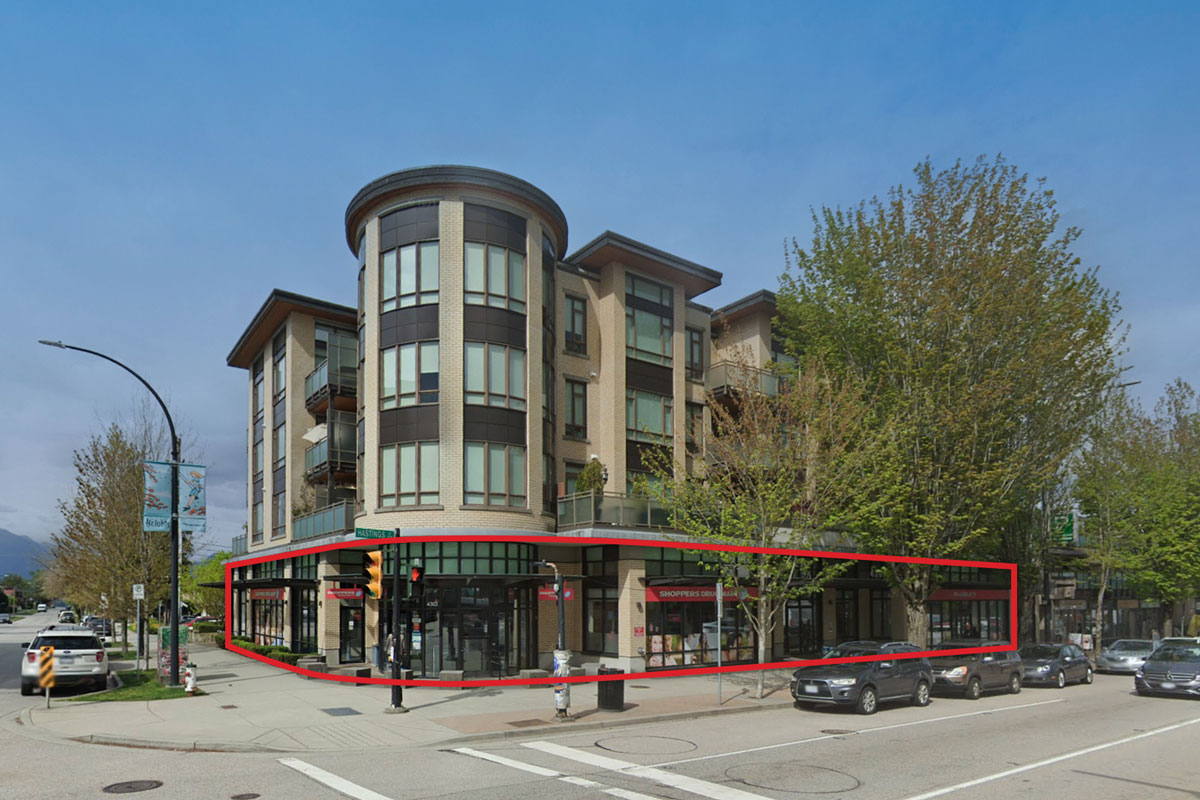
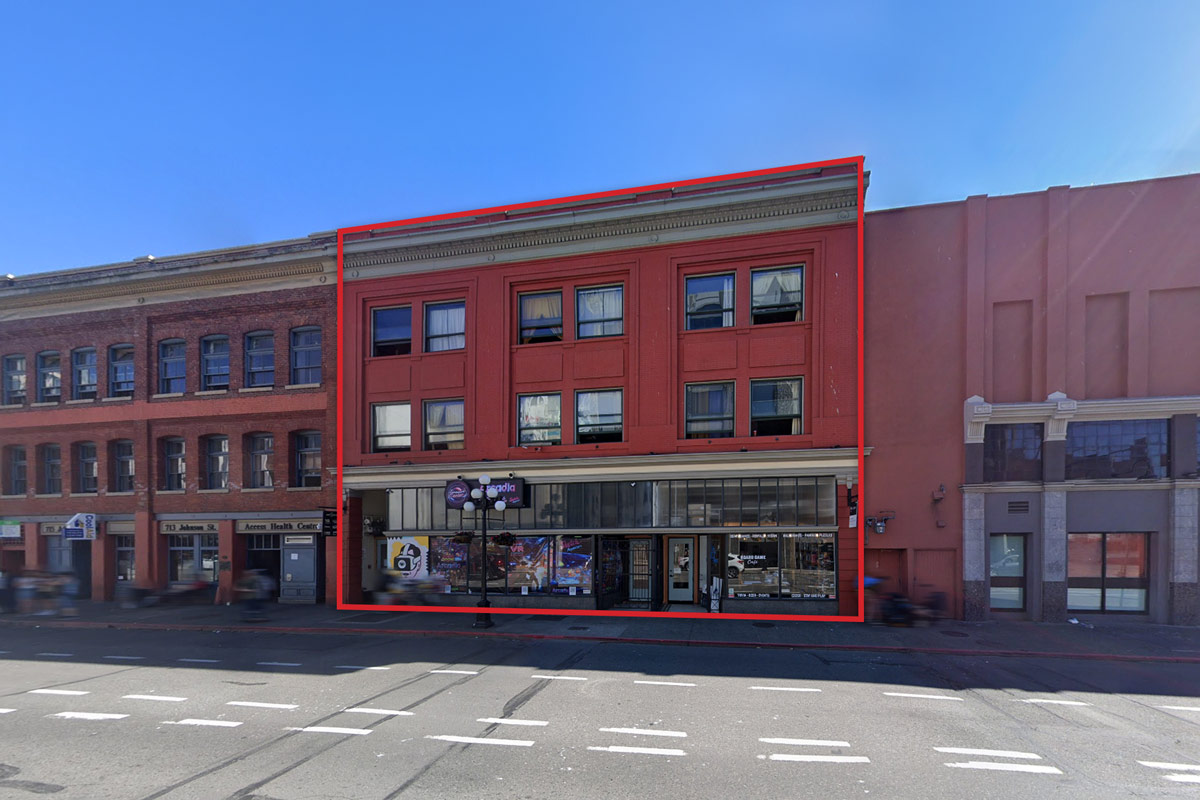
Retail has been the valley’s most dependable performer, and that predates the current recovery. Our own outlook heading into 2026 pointed to retail resilience as a defining feature of the BC market, with momentum from late 2025 carrying forward and a shrinking pipeline of new construction focusing demand on existing space. The second quarter gave us a concrete local example with a large component of Kelowna’s One Water development selling a 16,000 square feet portfolio of fully leased ground floor retail strata units to an investor. Additionally, Shelby Kostyshen and Jeff Hancock from our Kelowna office recently brought 8,226 square feet of retail strata product to market in downtown Kelowna. These trends are starting to surface in other areas of the Okanagan as well with steady demand in Vernon and Penticton.
In the North Okanagan, what we can observe is that industrial space makes up the largest share of Vernon’s commercial lease inventory, consistent with the city’s role as the service and distribution hub for the region, with available premises ranging from small bays to spaces approaching 38,000 square feet. What our agents are seeing on the ground will carry more weight than any third-party series for this part of the valley, and I expect that to remain true for some time.
As a Commercial Realtor, I pay as much attention to the questions clients ask as I do to the statistics. Twelve months ago, the most common question heard in our Kelowna office was whether values had further to fall. This quarter, the three questions I hear most often are:
That shift in tone, from defence to positioning, tells me as much about where this market is heading as any vacancy rate.
Moving forward, there are a few key risks to keep an eye on. The first is the ongoing trade and tariff dispute between Canada and the USA. We expect industrial leasing across the country to continue being cautious over the coming months as occupiers wait out the renegotiation of the Canada-United States-Mexico Agreement and any subsequent trade shocks. The second is that our market is still proportionately modest compared to large regions of the country. When a large mandate is filled or a tenant vacates a space, it can skew figures considerably, so we must continue to focus on the fundamentals of data.
The most important number in this quarter’s national data may also be the smallest one. Just 37,500 square feet of new office space was delivered across the entire country in the second quarter—the lowest level in fifteen years, with less than two million square feet remaining under construction and no meaningful new wave of development expected until the next decade.
When little new space is coming, the buildings that already exist become the whole market, and the regions that kept those buildings occupied through the downturn enter the recovery first. That is the Okanagan’s position today. This valley did not need a dramatic rebound this quarter because it never had a dramatic fall, and I am hopeful that as capital moves off the sidelines and back into higher performing assets, steady occupancy and steady demand will prove to be exactly what they look like: a head start.
Written by Nick Renton for William Wright Commercial.
¹Colliers Canada, Q1 2026 national market report, as reported by The Canadian Press (Sammy Hudes), “Commercial real estate market at turning point as vacancies drop,” April 20, 2026. castanet.net/news/Business/609858/
²Colliers Canada, Q2 2026 National Market Snapshot, released July 8, 2026. Via CNW/Newswire.ca.
This communication is not intended to cause or induce breach of an existing agency agreement. E&OE: All information contained herein is from sources deemed reliable, and have no reason to doubt its accuracy; however, no guarantee or responsibility is assumed thereof, and it shall not form any part of future contracts. Properties are submitted subject to errors and omissions and all information should be carefully verified. All measurements quoted herein are approximate.
ⓒ William Wright Commercial Real Estate Services 2026
Proudly designed by Burst Creative